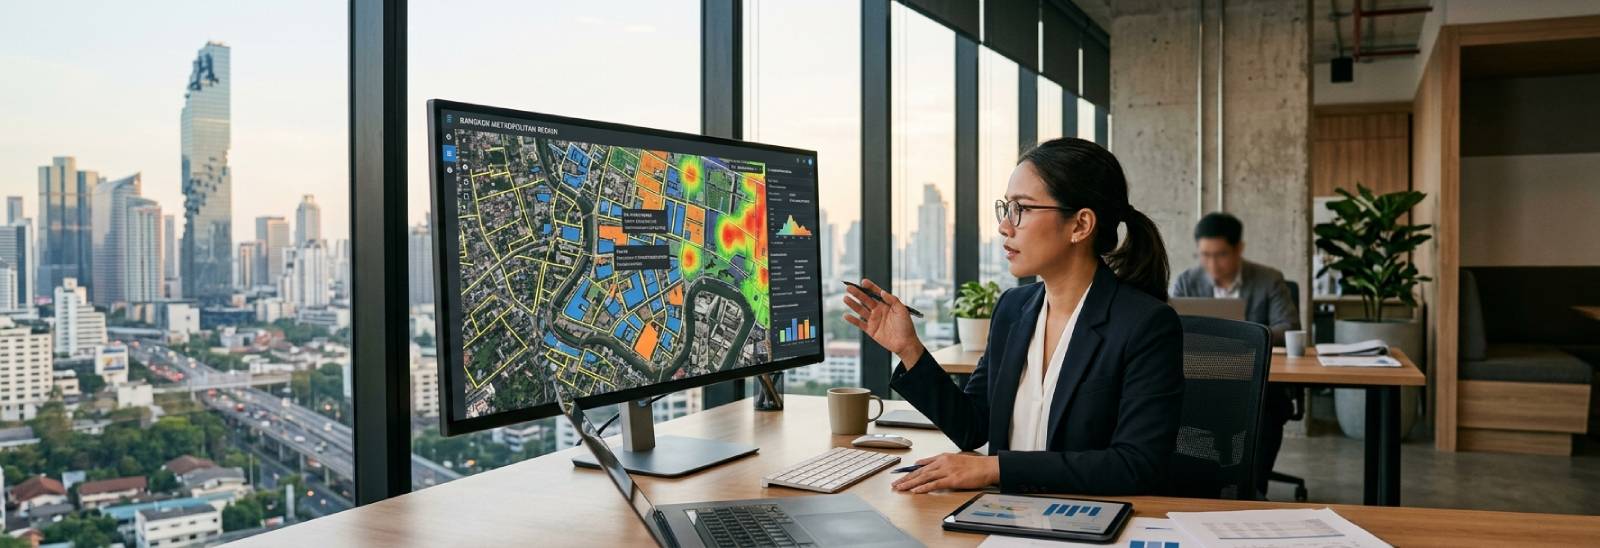
Thailand's administration of the Land and Building Tax (LBT) is undergoing a significant technological transformation. Local administrative authorities, particularly the Bangkok Metropolitan Administration (BMA), have increasingly adopted satellite imagery, aerial mapping technologies, and digital land-use analytics to improve the accuracy and efficiency of tax assessments. These technologies are designed to identify the actual utilization of land and buildings, enabling authorities to distinguish between agricultural, residential, commercial, and vacant properties more effectively.
This modernization aligns with the objectives of the Land and Building Tax Act B.E. 2562 (2019), which seeks to reduce speculative land holding and ensure that tax liabilities correspond to the actual use of property. Under the Act, vacant or unused land is subject to progressively higher tax rates, with additional increases every three years if the property remains undeveloped or unused, creating substantial financial exposure for long-term land banks.
However, while AI-assisted assessment improves administrative efficiency, it also introduces new challenges. Automated image interpretation cannot always accurately determine whether land is genuinely being used for agricultural purposes or whether temporary conditions have altered the visual appearance of a property. Consequently, taxpayers may receive assessments that do not fully reflect the factual circumstances on the ground.
AI Assessment Disputes: Why Physical Evidence Still Matters
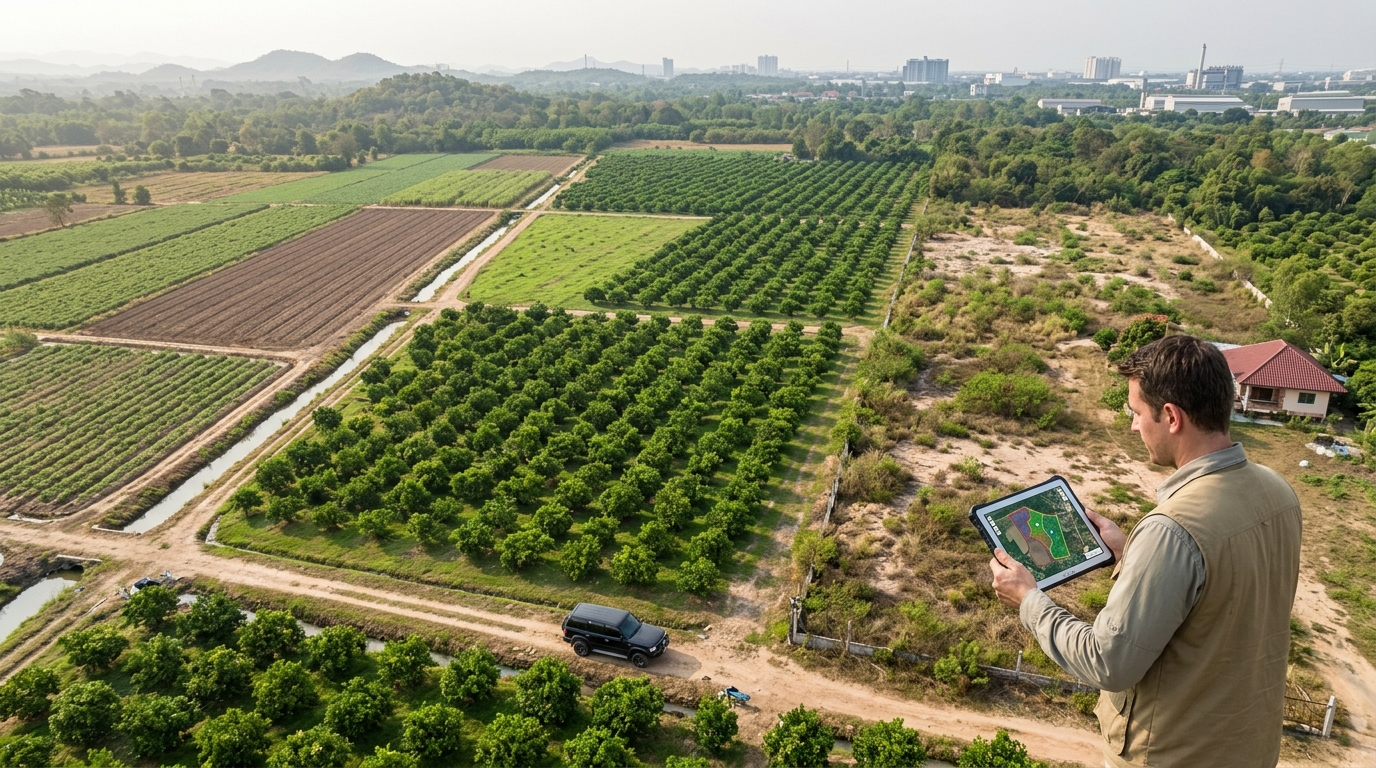
Although satellite imagery provides valuable data, taxation under Thai law remains fundamentally dependent on the actual facts and legal classification of property use rather than algorithmic interpretation alone. In practice, discrepancies frequently arise when digital imagery identifies land as vacant despite ongoing agricultural activities, seasonal cultivation cycles, or land preparation works that are not readily visible from aerial photographs.
Professional tax advisors therefore play a critical role in challenging incorrect assessments. A comprehensive dispute strategy often involves conducting physical site inspections, documenting actual land utilization, collecting photographic evidence, preparing cultivation records, obtaining supporting documentation from local authorities, and presenting technical explanations demonstrating that the statutory requirements for agricultural use have been satisfied.
The importance of these disputes extends beyond correcting a single year's assessment. If land is incorrectly classified as vacant, owners may become subject to significantly higher tax rates and progressive increases designed to discourage idle landholding. Timely objections supported by factual evidence can therefore generate substantial long-term tax savings while ensuring compliance with the legal framework.
Moreover, as local authorities increasingly rely on technology-assisted reviews, taxpayers should not assume that digital assessments are infallible. Proper documentation and proactive monitoring have become essential components of effective property tax governance.
Strategic Agricultural Conversion: Compliance Beyond Cosmetic Planting
One of the most sophisticated areas of LBT planning involves converting otherwise vacant land into qualifying agricultural use. While this strategy is entirely legitimate when implemented correctly, authorities have become increasingly vigilant against artificial arrangements designed solely to obtain lower tax rates without genuine agricultural activity.
The Ministry of Finance and related ministerial guidelines establish objective criteria for determining whether land qualifies as agricultural property. These criteria extend beyond merely planting a few trees and include minimum planting densities, crop types, maintenance standards, and evidence of genuine agricultural operations. For example, lime orchards must satisfy prescribed planting density requirements per rai and demonstrate actual cultivation consistent with regulatory expectations.
As enforcement becomes more sophisticated, simply placing scattered trees across a vacant plot is unlikely to withstand scrutiny. Authorities may examine satellite imagery over multiple years, conduct field inspections, review irrigation systems, evaluate maintenance conditions, and assess whether the agricultural activity appears commercially or practically sustainable.
Accordingly, tax advisors increasingly work alongside agricultural consultants, surveyors, and land management professionals to design compliant land-use plans that satisfy both regulatory requirements and the client's long-term investment objectives. The emphasis has shifted from superficial tax avoidance measures to evidence-based compliance supported by verifiable operational activities.
The Future of Property Tax Advisory in Thailand's Digital Economy
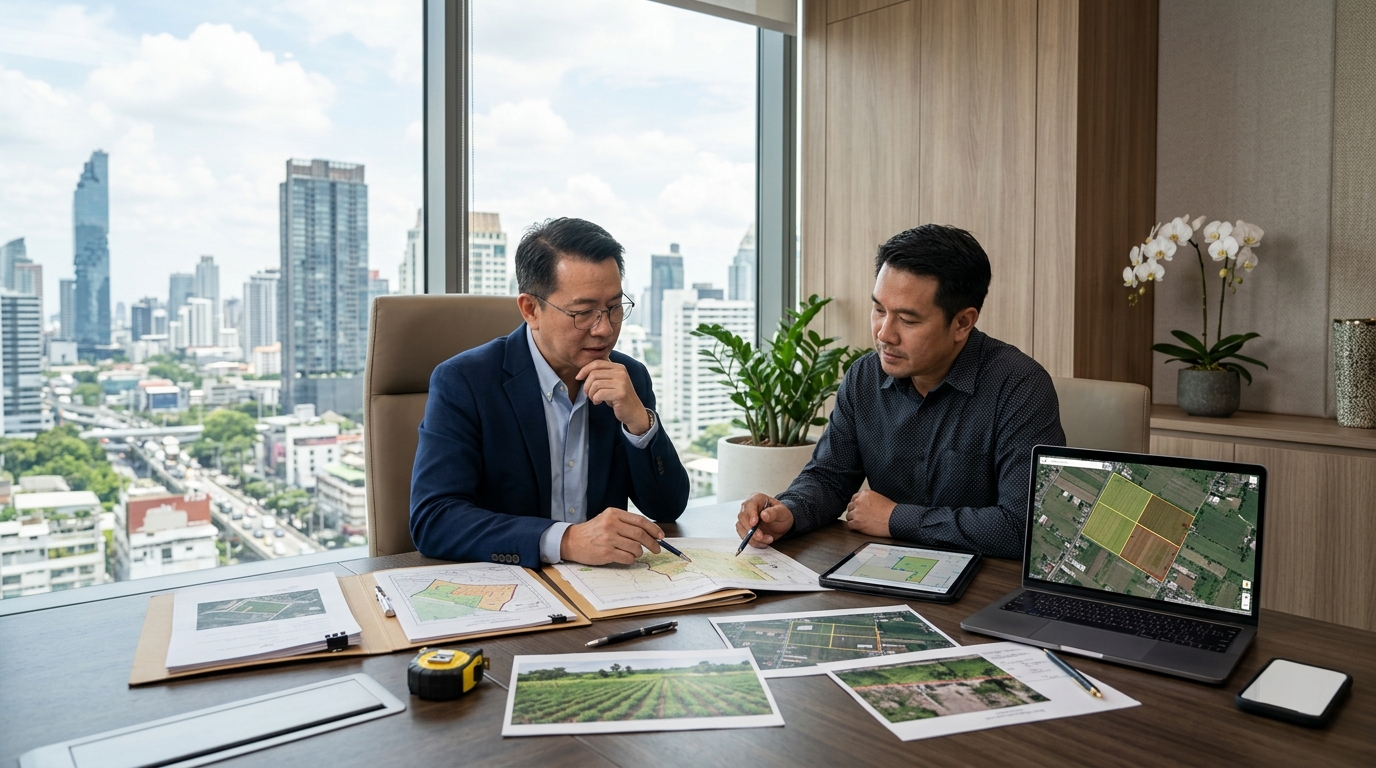
The evolution of AI-assisted tax administration represents a fundamental shift in how land ownership is monitored and taxed in Thailand. Rather than relying solely on annual declarations, authorities can now continuously compare digital imagery, historical land records, and administrative databases to identify potential inconsistencies.
For landowners, developers, family offices, and corporate investors holding substantial land portfolios, property tax management should no longer be viewed as a routine compliance exercise. It requires ongoing strategic planning, regular land-use reviews, documentation management, and early intervention before disputes escalate.
Professional advisors must likewise evolve beyond traditional tax filing services. Modern LBT advisory increasingly combines legal analysis, geographic information systems (GIS), remote sensing interpretation, agricultural compliance, evidentiary documentation, and dispute resolution techniques. The objective is not merely to reduce tax liabilities but to ensure that land classification accurately reflects genuine use while withstanding regulatory scrutiny.
As Thailand continues to digitalize tax administration, businesses that proactively align their land management practices with statutory requirements will be better positioned to mitigate risk, defend assessments, and optimize long-term property holding costs. In an environment where algorithms may initiate assessments but legal standards ultimately determine liability, comprehensive documentation and substantive compliance remain the strongest defenses against costly tax disputes.
