As Thailand continues to position itself as a regional digital asset hub, cryptocurrency taxation has evolved far beyond calculating gains at year-end. The convergence of regulatory oversight, blockchain transparency, and advanced data analytics means that every transaction now contributes to a permanent digital audit trail. For businesses, investors, and tax advisors, the challenge is no longer simply determining tax liability—it is demonstrating that every reported figure can be substantiated with defensible evidence.
The modern tax advisor has therefore become part accountant, part technology consultant, and part risk strategist, helping clients navigate an increasingly sophisticated compliance environment.
Digital Asset Transactions Demand Strategic Tax Planning, Not Just Tax Reporting
A common misconception among investors is that tax consequences arise only when cryptocurrency is converted into Thai Baht. In reality, the disposal or transfer of digital assets—including exchanges between cryptocurrencies—may constitute realization events depending on the applicable tax rules and available exemptions.
Thailand's evolving regulatory framework has introduced significant incentives for transactions conducted through Securities and Exchange Commission (SEC)-licensed digital asset operators, including temporary personal income tax exemptions for qualifying capital gains. However, eligibility depends on satisfying specific legal conditions and maintaining adequate documentation to support the taxpayer's position.
Consequently, tax planning must begin before transactions occur. Decisions regarding which platform to use, how assets are transferred between wallets, and when gains are realized can materially affect both compliance obligations and tax outcomes. Simply recording profits after the fact is no longer sufficient.
FIFO Cost Basis Is No Longer an Accounting Exercise—It Is a Risk Management Framework
Accurately determining capital gains requires identifying which assets have been disposed of and at what acquisition cost. Under accepted tax methodologies, many taxpayers apply the First-In, First-Out (FIFO) approach, whereby the earliest acquired digital assets are treated as the first sold.
While conceptually straightforward, FIFO becomes considerably more complex when investors operate across multiple exchanges, private wallets, decentralized finance platforms, staking protocols, and cross-chain ecosystems. Internal wallet transfers, token migrations, network fees, and wrapped assets can distort cost calculations if not properly reconciled.
For active traders and corporate treasury functions, manual spreadsheets rarely provide sufficient reliability. Instead, blockchain forensic platforms capable of reconstructing transaction histories across multiple networks have become indispensable tools for maintaining consistent cost basis calculations and supporting future tax examinations.
The objective is not merely computational accuracy but the creation of an auditable methodology that can withstand regulatory scrutiny.
Blockchain Analytics Is Reshaping Revenue Department Audits
Unlike traditional financial records, blockchain transactions are permanently recorded and publicly verifiable. As licensed exchanges strengthen customer reporting and governments continue investing in digital oversight capabilities, tax authorities are increasingly able to reconcile taxpayer declarations against blockchain activity and exchange data.
Artificial intelligence and blockchain analytics now enable regulators to identify inconsistencies that may previously have gone undetected, including unexplained wallet transfers, missing acquisition records, duplicated cost bases, or gains calculated using inconsistent methodologies.
This technological evolution fundamentally changes the nature of tax audits. Rather than relying solely on invoices and bank statements, future examinations may incorporate wallet tracing, transaction hash verification, and automated reconciliation across multiple platforms.
For taxpayers, maintaining comprehensive digital documentation—including exchange statements, wallet addresses, transaction identifiers, valuation records, and reconciliation schedules—is becoming one of the most effective safeguards against future disputes.
The Competitive Advantage Lies in Governance, Not Compliance
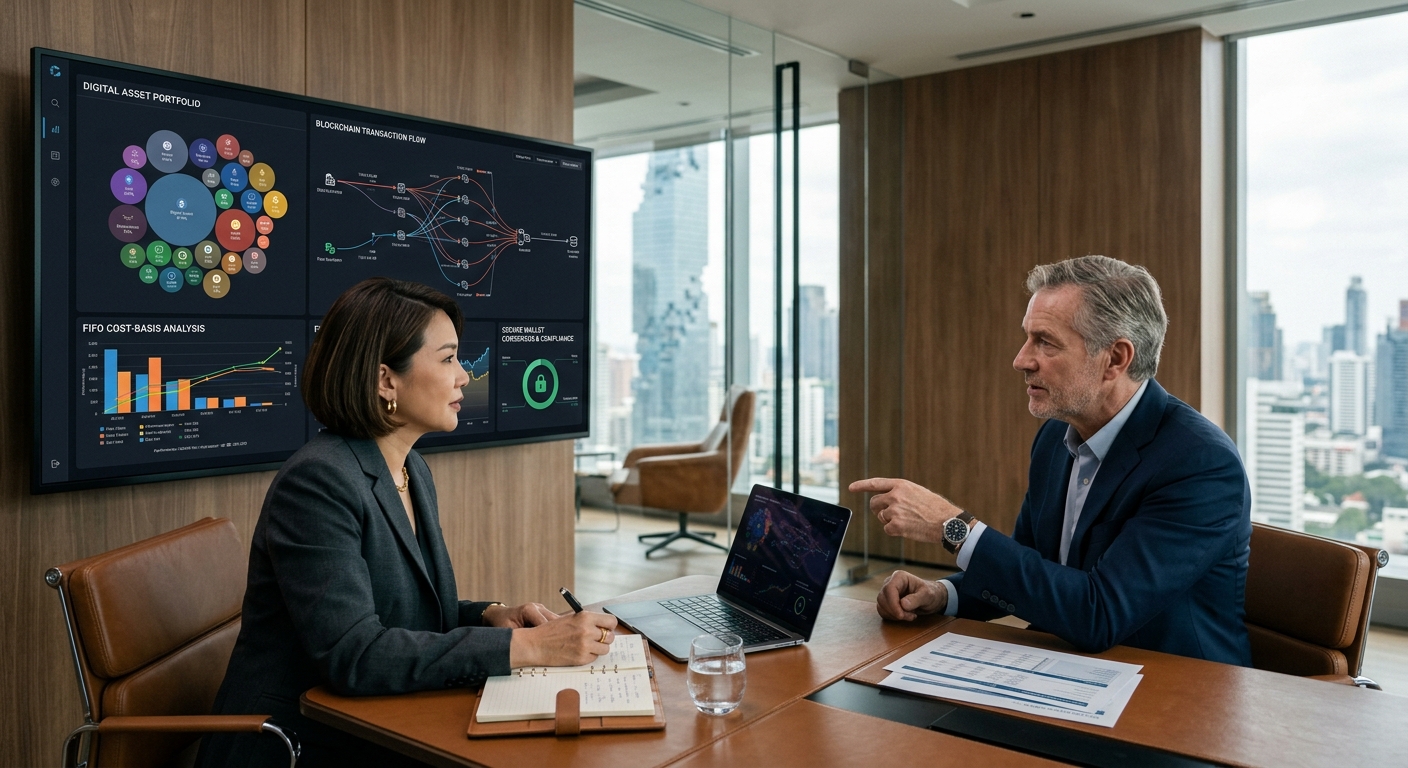
The most sophisticated organizations no longer view crypto taxation as an isolated reporting obligation. Instead, they integrate tax considerations into broader governance frameworks that encompass treasury management, internal controls, accounting policies, and regulatory compliance.
Tax advisors increasingly assist clients in designing digital asset governance models that define wallet ownership, establish documentation standards, automate transaction tracking, and implement standardized valuation methodologies before transactions occur. These proactive measures reduce audit risk, improve financial reporting accuracy, and ensure that available tax incentives can be confidently claimed.
As Thailand's digital economy continues to mature, competitive advantage will belong not to those who simply minimize taxes, but to those who can demonstrate complete transparency from acquisition through disposal. In an era where every blockchain transaction creates a permanent record, traceability has become one of the most valuable assets in tax compliance.
The future of crypto taxation in Thailand is not defined solely by tax rates or filing obligations—it is defined by data integrity. First-In, First-Out calculations, blockchain forensic analysis, and robust governance frameworks are rapidly becoming essential components of modern tax advisory.
For businesses and investors operating in digital assets, success will depend on more than understanding the law. It will require the ability to prove, with precision and consistency, how every transaction was executed, valued, and reported. In this new environment, blockchain transparency is no longer simply a technological feature—it is the foundation of credible tax compliance and long-term regulatory resilience.
