For many years, multinational corporations entering the Thai market routinely imported global contract templates containing extensive limitation of liability provisions, broad indemnities, and comprehensive hold-harmless protections. These clauses were often designed to shift substantial commercial risk away from the drafting party and onto its counterparty. While such approaches may remain effective in certain jurisdictions, their enforceability under Thai law has become increasingly uncertain.
Thailand's legal landscape has evolved significantly, particularly in the area of contractual fairness. Although freedom of contract remains a cornerstone of commercial law, Thai courts have consistently emphasized that contractual autonomy cannot be exercised in a manner that creates an unreasonable imbalance between the parties. This principle is reflected in the Unfair Contract Terms Act B.E. 2540 (1997), which grants courts broad authority to intervene where contractual provisions are considered unfair or unconscionable.
As a result, businesses can no longer assume that a carefully drafted liability clause will automatically be enforced simply because it was agreed between sophisticated commercial parties. The practical question facing legal teams today is whether the allocation of risk can withstand judicial scrutiny under Thailand's increasingly sophisticated approach to contractual fairness.
The Rise of the Proportionality Test
A defining feature of modern contract enforcement in Thailand is the growing emphasis on proportionality. Rather than focusing solely on the wording of a contractual provision, courts are increasingly concerned with whether the allocation of risk reflects a reasonable balance when viewed against the commercial realities of the transaction.
This development has important implications for limitation of liability clauses. Historically, suppliers often sought to cap liability at a relatively low amount, such as several months of service fees, regardless of the nature of the services provided or the potential consequences of a failure. Such provisions were frequently regarded as standard commercial practice and incorporated into agreements with little discussion.
However, contemporary judicial analysis extends beyond contractual convention. Courts may examine whether the liability cap bears a rational relationship to the foreseeable risks arising from the transaction. A limitation that appears commercially acceptable on paper may become difficult to justify where a serious breach results in substantial operational disruption, financial loss, regulatory exposure, or reputational damage.
This issue becomes particularly relevant where the breach arises from gross negligence, deliberate misconduct, or a failure to comply with statutory obligations. In such circumstances, a court may conclude that a liability cap effectively deprives the injured party of a meaningful remedy and therefore creates an imbalance inconsistent with the principles of fairness and good faith that underpin Thai contract law.
The trend reflects a broader judicial philosophy that commercial parties should remain accountable for risks that they are best positioned to control. Consequently, liability limitations are increasingly assessed not only from a contractual perspective but also from the standpoint of commercial reasonableness.
From Arbitrary Caps to Risk-Based Contracting
One of the most significant developments in sophisticated contract drafting is the movement away from arbitrary liability caps and toward risk-based allocation models. Rather than relying on traditional formulas or inherited template language, leading organizations are increasingly aligning contractual exposure with measurable commercial risks and available insurance coverage.
This approach provides a stronger justification for the limitation itself. A liability cap that corresponds to professional indemnity insurance, cyber liability coverage, or other established risk-transfer mechanisms is generally easier to defend than one selected without any apparent connection to the underlying transaction.
The distinction is particularly important in sectors involving technology services, cloud infrastructure, outsourced business processes, financial services, and personal data processing. In these industries, a contractual failure may trigger consequences that extend far beyond the immediate value of the contract. Regulatory investigations, data breaches, business interruption losses, and third-party claims can create exposures that significantly exceed annual service fees.
As Thailand's regulatory framework continues to mature, particularly under the Personal Data Protection Act (PDPA), courts are increasingly likely to evaluate whether contractual limitations appropriately reflect the seriousness of these risks. Businesses that attempt to contractually eliminate responsibility for foreseeable compliance failures may find that such provisions receive limited judicial sympathy.
The modern objective is therefore not simply to minimize liability but to establish a defensible allocation of risk that reflects the parties' respective ability to manage, mitigate, and insure against potential losses.
Strategic Considerations for International Businesses
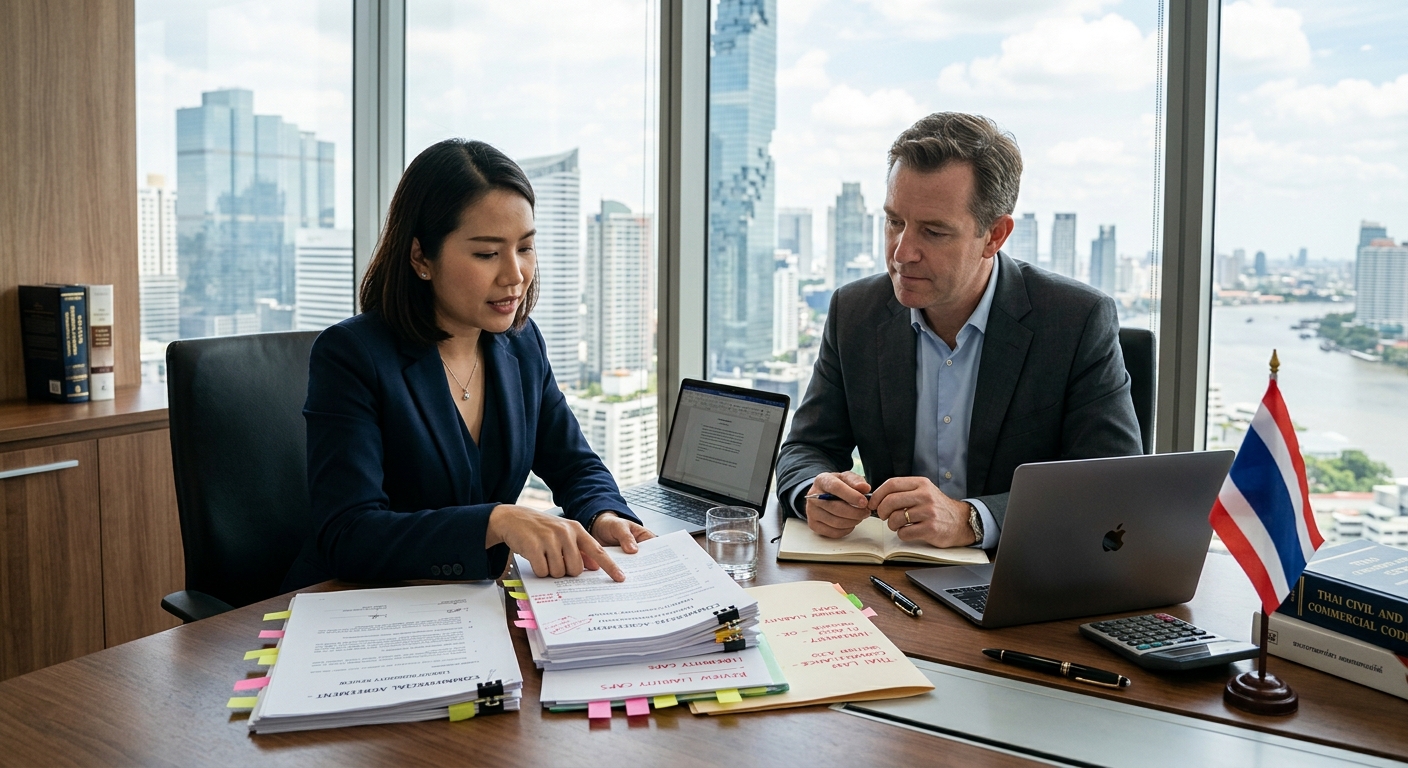
For foreign investors and multinational enterprises, the implications are clear. Contractual provisions that may be enforceable under English law, New York law, or other common law systems should not be assumed to produce identical outcomes in Thailand. Local legal principles, statutory protections, and public policy considerations remain highly influential in determining whether a contractual limitation will ultimately be upheld.
This reality requires legal teams to move beyond the traditional practice of adapting global precedents with minimal localization. Effective drafting now demands a deeper understanding of how Thai courts evaluate fairness, proportionality, and commercial reasonableness. Liability caps should be calibrated to the actual risks presented by the transaction, indemnity obligations should be carefully defined, and exclusions should be drafted with due regard to statutory and public policy limitations.
The most sophisticated agreements increasingly recognize that different categories of risk warrant different levels of protection. Rather than imposing a single blanket limitation, modern contracts frequently distinguish between ordinary contractual breaches and higher-risk matters such as data protection violations, intellectual property infringement, confidentiality breaches, fraud, and willful misconduct. Such differentiation demonstrates a balanced and commercially rational approach that is more likely to withstand judicial scrutiny.
The evolution of Thai contract law reflects a broader shift toward fairness-based enforcement and commercially rational risk allocation. The era of relying on aggressive boilerplate clauses to eliminate liability has largely passed. Courts are increasingly prepared to examine whether contractual provisions operate fairly in practice, regardless of how carefully they have been drafted.
For businesses operating in Thailand, the central challenge is no longer how to transfer the maximum amount of risk to a contractual counterparty. Instead, it is how to create a risk allocation framework that reflects the commercial realities of the transaction while remaining consistent with the principles of fairness, proportionality, and accountability recognized under Thai law.
In 2026, the strongest liability clauses are not necessarily the most restrictive. They are the ones that can be justified as reasonable, balanced, and proportionate when viewed through the lens of judicial review. As contractual disputes become increasingly complex and regulatory expectations continue to rise, proportionality has emerged as the defining principle of enforceable risk allocation in Thailand.
